Living Trust vs Will in Virginia: What to Know
Get clear answers on living trust vs will in Virginia, including how each works, key differences, and tips for choosing the right estate plan for your needs.
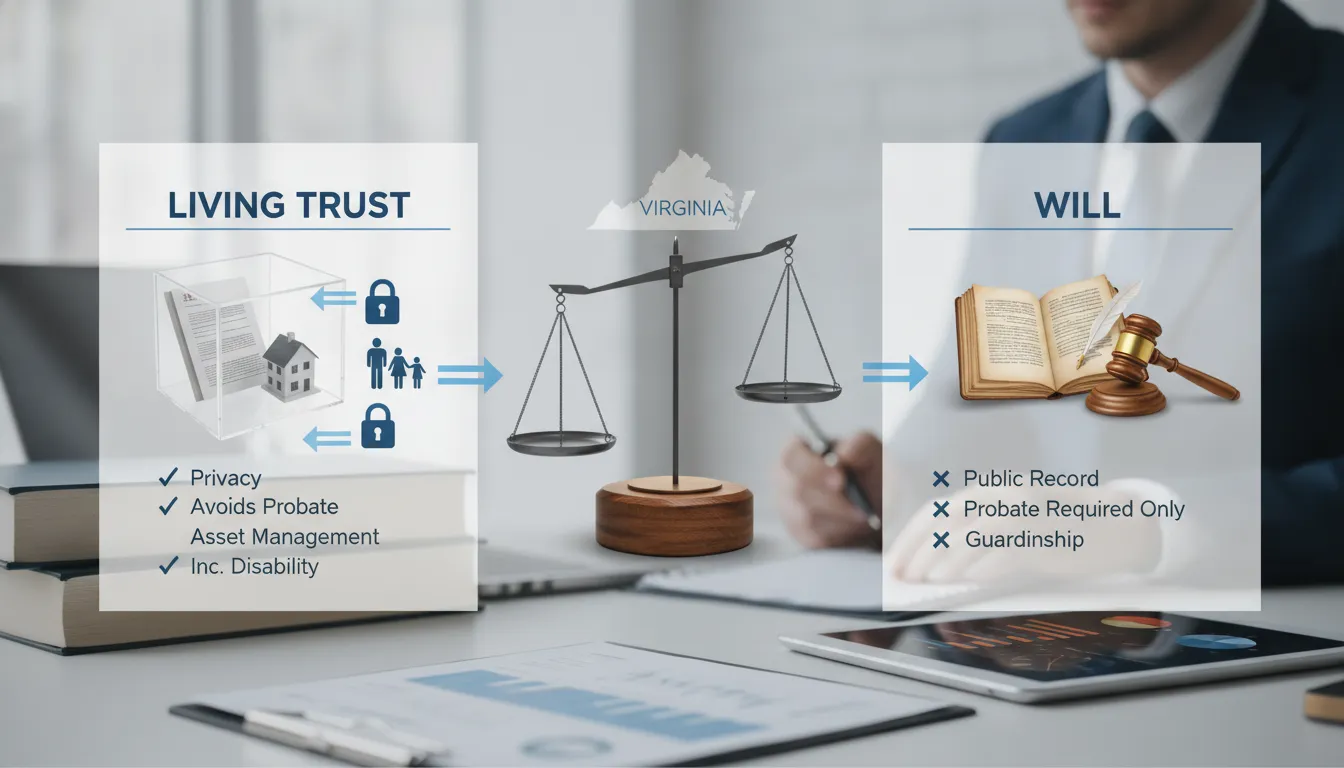
The best estate plan is not always the one with the most documents. It is the one that reflects your family, property, and priorities. For some Virginia residents, a will offers a clear and practical way to distribute assets. Others may benefit from a funded living trust, especially when they own property in multiple states, have a blended family, or want detailed instructions for a future incapacity. The decision involves more than estate size. If you are comparing living trust vs will in virginia, learn how ownership, beneficiary forms, probate, and family circumstances can affect the result.
Key Takeaways
- Wills and living trusts have different roles: A will can name a guardian, appoint an executor, and direct property subject to probate. A living trust can manage funded assets during incapacity and after death.
- A trust must be properly funded and coordinated: Retitle eligible assets, review beneficiary designations, and connect the trust with a pour-over will, financial power of attorney, and advance medical directive.
- Your family and property should guide the decision: Consider minor children, blended families, special needs, multiple properties, business interests, privacy, and probate when creating a Virginia estate plan.
How Does a Living Trust Differ From a Will in Virginia?
A living trust and a will can both direct what happens to your property after death, but they operate at different times and serve different purposes. A revocable living trust is created during your lifetime. You can transfer assets into the trust, manage them as the trustee, and name a successor trustee to take over if you become unable to manage your affairs. After your death, the successor trustee distributes the trust property according to your instructions.
A will generally takes effect after death. It names the person you want to handle your estate, identifies your beneficiaries, and can nominate a guardian for minor children. Assets controlled only by a will typically pass through Virginia probate, the court-supervised process for administering an estate.
The right choice depends on more than the size of your estate. Family relationships, real estate ownership, privacy concerns, incapacity planning, beneficiary needs, and the possibility of future changes all deserve attention. Many Virginia estate plans use both documents: a funded trust for assets transferred into the trust and a pour-over will as a safety net for assets left outside it. An attorney can also coordinate these documents with beneficiary designations, powers of attorney, and medical directives.
How a Revocable Living Trust Works During Life and After Death
A revocable living trust is established and funded while you are alive. In many cases, you serve as the initial trustee and continue using the trust property as you normally would. Because the trust is revocable, you can usually amend or revoke it during your lifetime, subject to the trust terms and applicable Virginia law.
If you become incapacitated, a successor trustee can manage assets titled in the trust without waiting for a court to appoint a conservator. After your death, the successor trustee identifies and protects trust assets, pays appropriate expenses, and distributes the remaining property to the named beneficiaries. Properly funded trust assets can often avoid probate, which may make administration more private and efficient. Learn more about how revocable living trusts work in Virginia.
The key phrase is “properly funded.” Signing the trust document alone does not transfer ownership of your bank accounts, investments, or real estate. Those assets must be retitled or otherwise coordinated with the trust when appropriate.
How a Virginia Will Controls Probate Assets
A will states your wishes for property that passes through your estate after death. It can name an executor, identify beneficiaries, describe how personal property should be distributed, and nominate a guardian for minor children. It can also create a testamentary trust that begins after death for a child or another beneficiary who may need continuing support.
A will does not usually control assets that pass by beneficiary designation, joint ownership, or a trust. For other property, the executor presents the will to the appropriate Virginia circuit court clerk and begins the probate process. The executor then gathers and protects estate assets, provides required notices, handles valid debts and expenses, and distributes the remaining property under the will.
Probate filings are generally public, and the process may take longer when an estate includes disputes, business interests, real estate, creditor issues, or tax concerns. A will can still be the most practical choice for a straightforward estate, particularly when the family and asset structure is simple. Virginia’s probate process includes specific procedures that an executor must follow.
What Trustees, Successor Trustees, Executors, and Personal Representatives Do
The person managing a trust is called the trustee. During your lifetime, you may act as your own trustee. A successor trustee takes over when you become incapacitated or die. That person may need to identify trust assets, keep accurate records, pay expenses, communicate with beneficiaries, and distribute property according to the trust terms.
The person handling a will-based estate is usually called an executor. In Virginia, the broader term personal representative may include an executor named in a will or an administrator appointed when someone dies without a valid will. The personal representative works through probate, collects and protects estate assets, addresses creditor claims, files required documents, and transfers property to the proper beneficiaries.
These roles require judgment and organization, so the best choice is not always the oldest child or closest relative. Consider whether the person lives nearby, can manage financial details, communicates clearly, and can make decisions fairly. A trust may also name a professional or corporate fiduciary if the estate is complex or family conflict is likely. Virginia’s probate resources provide additional information about estate administration.
How Courts Approve Guardian Nominations for Minor Children
A living trust can manage money for a child, but it does not name the person who will provide the child’s daily care. In Virginia, a parent generally uses a will to nominate a preferred guardian for minor children. The nomination gives the court important information about the parent’s wishes, but it does not guarantee that the nominated person will automatically receive custody.
If both parents have died or cannot care for a child, the court considers the child’s best interests and other relevant circumstances. The judge may review the proposed guardian’s relationship with the child, ability to provide care, home environment, and willingness to serve. The court may also consider competing nominations or concerns raised by relatives and other interested parties.
Review guardian nominations after a marriage, divorce, separation, adoption, birth, relocation, or the death of a proposed guardian. A Virginia will can nominate a guardian while a trust can provide instructions for managing the child’s inheritance.
How Revocable and Irrevocable Trusts Differ
A revocable trust can usually be changed, amended, or revoked by the person who created it. You can generally serve as trustee, retain control of the trust property, and change beneficiaries as your circumstances develop. This flexibility makes revocable trusts useful for probate planning, privacy, incapacity planning, and ongoing asset management.
An irrevocable trust usually cannot be changed or canceled freely after it is created. Depending on its terms and administration, it may serve goals such as asset protection, charitable giving, tax planning, or special-needs planning. The person creating the trust may give up significant control, which is why the structure requires careful legal and financial review.
A revocable trust typically does not protect your assets from your own creditors because you retain control and benefit from the property. It also does not automatically reduce estate taxes. The appropriate trust depends on its purpose, not simply on its label. Compare revocable and irrevocable trusts before deciding which structure may fit your circumstances.
How Ownership and Beneficiary Designations Affect Each Plan
Estate documents do not control every asset in the same way. A trust generally controls property titled in the trust’s name or property directed to the trust under a coordinated account or transfer arrangement. If you sign a trust but leave a house, investment account, or bank account in your individual name, that asset may not receive the trust’s probate-avoidance benefits.
Beneficiary designations can also override instructions in a will or trust. Retirement accounts, life insurance policies, payable-on-death accounts, and transfer-on-death accounts commonly pass directly to the named beneficiary. Jointly owned property may pass to the surviving owner under the ownership agreement. These arrangements can work well, but outdated forms can send assets to an ex-spouse, a deceased beneficiary, or someone who cannot manage an inheritance.
Review titles and beneficiary designations whenever you create or revise an estate plan. A funded revocable trust and pour-over will often work together, but the documents must match the way your assets are actually owned.
What Each Document Covers During Incapacity and What It Does Not
A revocable living trust can provide a plan for managing trust assets if you become unable to manage them yourself. The successor trustee steps in under the trust terms and handles property owned by the trust. This arrangement may reduce the need for court-supervised conservatorship, but it does not give the successor trustee authority over assets that were never transferred to the trust.
A will generally does not operate during your lifetime. It cannot authorize someone to pay your bills, manage your investments, or make financial decisions after you become incapacitated. Those responsibilities are usually addressed through a durable financial power of attorney. The agent named in that document may manage assets outside the trust, depending on the document’s authority and the financial institution involved.
Neither a trust nor a will serves as a complete medical decision-making document. An advance medical directive and health care instructions address treatment preferences and identify the person you want to make medical decisions when you cannot communicate. A coordinated estate plan should account for trust assets, non-trust assets, financial authority, medical decisions, and family responsibilities. Virginia’s advance medical directive statute provides additional information about this separate document.
What Advantages Does a Living Trust Offer in Virginia?
A revocable living trust can give a Virginia family greater control over how assets are managed during life and distributed after death. You create the trust while you are alive, usually serve as your own trustee, and name a successor trustee to step in if you become unable to manage your affairs or after your death.
Unlike a will, a living trust can address certain needs during your lifetime as well as after death. It may help keep properly funded assets out of probate, provide continuity if you become incapacitated, and give a trustee detailed instructions for managing an inheritance. These features can be especially useful for families with minor children, blended families, multiple properties, or complex financial interests.
A trust is not automatically the best choice for every estate. Its benefits depend on how the trust is written, which assets are transferred into it, and whether the rest of the estate plan is coordinated with it. A trust also works only as intended when its ownership records, beneficiary designations, and instructions remain current. With careful preparation and maintenance, however, a living trust can address several concerns that a will alone may not.
Avoid Probate for Properly Funded Trust Assets
Assets owned by a properly funded living trust generally do not pass through the Virginia probate process when you die. Instead, the successor trustee follows the trust instructions and transfers or manages the assets for the beneficiaries. This can reduce court involvement and may allow distributions to happen more privately and efficiently.
The key phrase is “properly funded.” Signing the trust document alone does not move your bank accounts, investments, real estate, or business interests into the trust. Ownership must be changed when appropriate, and beneficiary designations should be reviewed. A Virginia estate planning attorney can help identify which assets to retitle and which should remain outside the trust.
Some assets already bypass probate through joint ownership, payable-on-death instructions, or beneficiary forms. Those designations still need to match the trust plan. If they conflict, the account or policy may pass according to its separate contract rather than the instructions in the trust.
Protect Privacy Within Important Limits
A Virginia probate file is generally available as a public court record. Trust administration usually takes place privately between the trustee and beneficiaries, which can help keep details about family relationships, property, and inheritances out of the public probate file. This may be useful for families who own businesses, valuable real estate, or other assets they do not want listed in court records.
Privacy is not absolute. A trust may become part of a court dispute, and certain information may still be disclosed to beneficiaries, government agencies, creditors, or taxing authorities. Trust-owned real estate also requires properly prepared deeds, and those deeds may appear in public land records.
As Virginia trust litigation guidance explains, trusts can support estate administration and may avoid the cost and process of probate, but they do not remove every legal requirement. Clear instructions and careful recordkeeping remain important.
Manage Trust Assets During Incapacity
One practical benefit of a revocable living trust is continuity. While you have capacity, you can manage the trust assets yourself. If illness, injury, or another condition prevents you from doing so, your named successor trustee can take over according to the trust terms.
This arrangement may reduce the need for a court-supervised conservatorship involving assets held in the trust. The successor trustee can pay bills, manage investments, maintain property, and handle other trust responsibilities without waiting for a probate proceeding after your death.
A trust does not replace every incapacity document. Assets that remain outside the trust may still require a durable financial power of attorney. Medical decisions generally require an advance medical directive or health care authorization. An effective plan coordinates the trust with these documents so your family knows who may act and what authority that person has.
Provide Ongoing Control for Minors and Vulnerable Beneficiaries
A trust can prevent a child or another vulnerable beneficiary from receiving a large inheritance all at once. Instead, the trustee can use trust assets for appropriate needs, such as education, housing, health care, and daily support. The trust can also establish ages or milestones for later distributions.
This structure may provide more protection than leaving assets directly to a minor. A trustee can manage the property until the beneficiary reaches the age selected in the trust document. The trustee can also apply judgment when a beneficiary has difficulty managing money or needs continued assistance.
Special circumstances require careful drafting. A beneficiary who receives needs-based public benefits may require a special needs trust rather than a standard inheritance trust. The trust should explain the trustee’s authority, distribution standards, and backup arrangements. Virginia trust planning guidance describes how a trustee may manage a child’s inheritance and pay for education, health care, and other needs.
Support Blended Families and Staged Inheritances
Blended families often need more detailed planning than a simple “everything to my spouse, then to my children” approach. A living trust can establish how assets will be used during the surviving spouse’s lifetime and who will receive what remains later. This can help coordinate provisions for a current spouse, children from a prior relationship, stepchildren, or other beneficiaries.
The trust can also stage distributions instead of giving each beneficiary an immediate lump sum. For example, it may provide funds for a child’s education, allow the trustee to pay living expenses, and distribute the remaining inheritance in portions at selected ages. The document can name backup trustees and explain what happens if a beneficiary dies before receiving the full amount.
These provisions must be drafted with precision. A surviving spouse may need access to trust property, while the person creating the trust may also want to preserve an inheritance for children from an earlier relationship. Guidance on revocable trusts in Virginia addresses planning for spouses, stepchildren, and children from prior relationships.
Reduce Ancillary Probate for Out-of-State Real Estate
Owning real estate in more than one state can create an additional probate issue. If property outside Virginia remains in your individual name when you die, the state where that property is located may require a separate probate proceeding. This is often called ancillary probate.
Transferring eligible out-of-state real estate to a properly prepared living trust may allow the successor trustee to manage or transfer it without a separate court proceeding in that state. This can reduce administrative work for the family and help keep the overall plan organized.
Real estate transfers require state-specific review. Each state has its own deed, recording, tax, and homestead rules, and some properties may have restrictions on ownership changes. As the discussion of wills and trusts in Virginia explains, a trust may help avoid separate probate for real estate located in multiple states, but the transfer must be completed correctly.
Coordinate Businesses, Multiple Properties, and Complex Assets
A living trust can bring structure to an estate that includes a closely held business, several properties, investment accounts, valuable personal property, or other complicated assets. The trust may explain who manages each asset, how income is handled, and when or how property should be sold or distributed.
Business interests require additional care. The trust, operating agreement, buy-sell agreement, insurance policies, and business records should work together. A transfer may require approval from other owners or compliance with the company’s governing documents. The same applies to real estate, partnership interests, and assets subject to lender restrictions.
A trustee may need detailed instructions and access to current records to carry out the plan. Virginia trust planning guidance identifies business interests, investments, and specific property as assets that may benefit from detailed trust instructions. An attorney can review ownership documents and help coordinate the trust with the broader estate plan.
What Limitations Does a Living Trust Have Compared With a Will?
A revocable living trust can offer useful benefits, but it is not automatically better than a will. It may help keep properly funded assets out of probate, provide a plan for managing property during incapacity, and keep some estate details private. Those benefits come with additional responsibilities, including transferring assets into the trust, maintaining records, and coordinating the trust with beneficiary designations and other legal documents.
A will may be appropriate for a straightforward Virginia estate, particularly when assets are limited and beneficiaries are adults. A living trust may require more planning and expense at the beginning, so the right choice depends on your family structure, property, financial accounts, and long-term goals.
It is also important to understand what a revocable trust does not do. It generally does not protect your assets from your own creditors, automatically reduce taxes, or eliminate every possible court proceeding. A trust also cannot replace documents that address guardianship, financial decisions during incapacity, or medical care. Speaking with a Virginia Beach estate planning attorney can help you compare the costs and benefits of each option before you prepare or revise your plan.
Account for Drafting, Retitling, and Administration Costs
A living trust often costs more to create than a basic will because the plan may involve additional legal documents, asset transfers, beneficiary coordination, and instructions for managing property. You may need to retitle real estate, bank accounts, or investment accounts in the trust’s name. These steps can take time and may involve recording fees or requirements set by a financial institution.
There may also be ongoing administrative work. The trustee must keep accurate records, manage trust property, and follow the trust’s instructions. A will usually has fewer setup requirements, although the estate may later incur probate and administration costs. A Virginia estate planning attorney can help compare the likely costs of each plan based on your assets, family circumstances, and goals.
Fund the Trust to Avoid an Unfunded Plan
Creating a trust is only part of the process. To receive the trust’s intended benefits, you generally need to transfer appropriate assets into it. This process is called funding. Depending on the asset, funding may involve changing an account owner, preparing and recording a new deed, or coordinating instructions with a bank or investment company.
An unfunded trust may not control property that remains in your individual name. Those assets could still pass through probate, even if the trust document explains how you want them distributed. As Virginia trust guidance explains, funding is a key step in connecting the trust to the assets it is meant to govern. Keep a current list of trust-owned property and review it after buying, selling, or refinancing assets.
Maintain Records and Prepare Successor Trustees
A living trust requires clear, accessible records. The trustee should be able to identify trust property, locate account information, understand recurring expenses, and find the current estate planning documents. If you serve as your own trustee, your successor trustee may need to step in if you become incapacitated or after your death.
Choose a successor trustee who is responsible, organized, and willing to handle financial matters. That person should know where to find the trust, deeds, account statements, insurance information, and professional contacts. You can provide written instructions without placing passwords or sensitive information directly in the trust. A well-prepared successor trustee plan may reduce unnecessary court involvement during incapacity, as Virginia estate planning attorneys explain.
Understand Why Revocable Trusts Usually Do Not Protect Assets From Creditors
A revocable living trust generally does not protect your assets from your own creditors. You retain the ability to change or cancel the trust and usually continue to control the property during your lifetime. Because you still control those assets, creditors may generally treat them as available to satisfy valid claims.
This limitation is easy to miss because the word “trust” can suggest asset protection. A revocable trust is mainly an organization and management tool, not a shield against lawsuits, debts, or creditor claims. Different rules may apply to irrevocable trusts and other planning structures, but giving up control can create significant legal and practical consequences. Review Virginia creditor and trust considerations with an attorney before transferring assets for asset protection purposes.
Understand Why Revocable Trusts Do Not Automatically Reduce Taxes
A revocable living trust does not automatically reduce income, estate, or capital gains taxes. Because you typically retain control over the trust property, the trust is often treated as part of your estate for tax purposes. Whether taxes apply depends on the value and type of assets, ownership arrangements, beneficiary designations, and the tax laws in effect when planning is needed.
Tax planning may require a different trust structure or additional strategies. Those options can affect control, flexibility, reporting, and access to assets. Avoid choosing a trust solely because someone says it will reduce taxes. Instead, ask how the proposed plan works with your property and family goals. Virginia trust planning guidance can help clarify what a revocable trust does and does not accomplish.
Recognize That Trusts Do Not Eliminate Every Court Proceeding
A trust may keep properly funded assets out of probate, but it does not guarantee that your family will never deal with a court. Disputes, creditor claims, questions about capacity, guardianship matters, and assets outside the trust can still require legal proceedings. A trust also cannot control property that was never transferred to it or that passes under a separate beneficiary designation.
A pour-over will provides a backup by directing certain assets left outside the trust to the trust after death. Those assets may still need to pass through probate before the transfer occurs. As Virginia will and trust guidance explains, a pour-over will supports the trust plan, but it does not replace the need to fund the trust correctly.
Correct Myths About Trust Permanence, Cost, and Wealth
A revocable living trust is not permanent during your lifetime. You can usually amend or revoke it while you have the legal capacity to do so. It is also not reserved only for wealthy families. People with minor children, blended families, out-of-state property, privacy concerns, or complicated beneficiary needs may find a trust helpful.
At the same time, a trust is not a universal solution. It may not be worthwhile if your estate is simple, your beneficiaries are capable adults, and avoiding probate is not a major concern. The decision should reflect your family structure and the way you own property, not a sales pitch or a fixed asset threshold. Virginia estate planning information can help you compare common trust uses with their limitations.
Use a Will, Power of Attorney, and Medical Directive Alongside the Trust
A trust usually works best as part of a coordinated estate plan. A pour-over will can address property not transferred to the trust and may name your preferred guardian for minor children. A durable financial power of attorney can authorize someone to manage assets that remain outside the trust or handle tasks the trustee cannot perform.
An advance medical directive addresses health care decisions and treatment preferences if you cannot communicate. These documents serve different purposes, so one does not replace the others. Virginia provides statutory requirements for documents such as an advance medical directive and financial power of attorney. An attorney can coordinate these documents with your trust, beneficiary forms, property titles, and family circumstances.
How Does Probate Work for a Virginia Will?
Probate is the court-supervised process for administering assets that pass under a person’s will. In Virginia, probate generally takes place through the circuit court clerk’s office in the city or county where the deceased person lived. The court does not rewrite the will. Instead, it recognizes the document, qualifies the executor, and provides a legal process for collecting assets, paying valid debts and expenses, and distributing property to beneficiaries.
Probate usually applies to assets owned solely by the deceased person that do not have another transfer method. These may include individually owned bank accounts, real estate, vehicles, and personal property. Other assets may pass outside probate through beneficiary designations, joint ownership, or a properly funded living trust. Reviewing how each asset is titled is therefore just as important as reviewing the will.
The process may be relatively straightforward when the estate is modest, the will is clear, and beneficiaries agree. It can take longer when the estate includes real estate, business interests, creditor claims, tax concerns, family disagreements, or property in another state. The Virginia Judicial System’s probate resources provide general information about the process, but they do not replace legal advice for a specific estate.
File the Will and Qualify the Executor With the Circuit Court Clerk
The executor named in the will generally begins by presenting the original will to the circuit court clerk in the Virginia city or county where the deceased person lived. The clerk reviews the document and handles the qualification process. If the will is accepted and the executor is eligible and willing to serve, the executor qualifies and receives authority to act for the estate.
The executor may need to provide information about the deceased person, the beneficiaries, and the estimated value of the estate. Virginia may also require a bond, although the will or applicable law may affect whether a bond is necessary. After qualifying, the executor can collect estate property, open an estate account, communicate with beneficiaries, and take other steps required to administer the estate.
The executor must also meet important deadlines. An inventory is generally due within four months after qualification, and the first accounting is generally due within 16 months. The specific requirements may depend on the estate and the local clerk’s procedures. An executor should review the Virginia probate process and seek legal guidance before filing.
Handle Notice, Inventory, Creditor Claims, Debts, Taxes, and Accounting
After qualification, the executor identifies and values probate assets, protects estate property, and provides required notice to beneficiaries and other interested parties. The executor also prepares an inventory describing the estate’s assets and their values. Complete records matter because the executor may need to explain how property was collected, managed, and distributed.
The executor must address valid debts and expenses before distributing property. These may include funeral expenses, final medical bills, mortgages, credit card balances, taxes, insurance, and administration costs. Virginia generally does not impose a separate inheritance tax, but federal estate tax or other tax filings may apply depending on the estate and the deceased person’s circumstances.
Creditors may have an opportunity to present claims. The executor must evaluate whether those claims are valid and payable from estate assets. The executor also prepares accountings that show money received, payments made, and distributions. The Virginia Code provisions on fiduciary accountings outline important responsibilities, although the proper procedure depends on the estate’s facts.
Understand How Estate Complexity Affects Probate Timing and Costs
Virginia does not impose one probate timeline for every estate. A simple estate with clear records, few assets, and cooperative beneficiaries may move through administration efficiently. An estate involving contested claims, several properties, business interests, tax questions, or difficult-to-locate beneficiaries may take substantially longer.
Some estates may take six to 18 months to administer, while more complicated estates can take longer. Real estate sales, creditor disputes, litigation, tax filings, and missing records can all delay distribution. Executors should avoid promising beneficiaries a specific payment date before debts, taxes, claims, and required accountings have been addressed. Distributing property too early can create personal risk if the estate later lacks funds to pay a valid obligation.
Probate costs may include court fees, bond premiums, appraisal charges, accounting fees, attorney fees, property maintenance, and taxes. Some estimates place total probate costs at approximately 3% to 7% of an estate’s value, but that is not a Virginia fee schedule and will not apply to every estate. The Virginia circuit court fee schedule identifies certain court charges, while professional fees depend on the work required.
Consider How Probate Expenses and Delays Affect Beneficiaries
Beneficiaries generally do not receive probate property immediately after a loved one’s death. The executor must first determine what the estate owns, protect the property, pay appropriate expenses and debts, resolve creditor claims, and complete required filings. If the estate includes a home or other property that must be sold, distribution may depend on the sale process and the condition of the market.
Administration expenses are paid from estate assets, reducing the property available to beneficiaries. These expenses may include legal services, appraisals, insurance, repairs, storage, accounting, and real estate costs. Delays can also create practical difficulties when beneficiaries are waiting for funds to pay housing, education, or other expenses.
Beneficiaries can help by responding promptly to the executor, providing current contact information, and raising concerns in writing. They should also understand that an executor has a duty to administer the estate according to the will and Virginia law, not simply distribute property as quickly as possible. When disagreements arise, early advice from a Virginia estate planning attorney may help prevent a manageable issue from becoming a costly dispute.
Weigh Public Filings Against Privacy
Probate generally creates a court record. The will and other probate filings may be available to people who request them, although access can depend on the document and the court’s procedures. Families who prefer greater privacy should understand that a will-based plan may disclose information about the estate, beneficiaries, and administration.
A revocable living trust can keep many estate details outside the probate court record when assets are properly transferred to the trust. This does not make every estate matter private. Deeds, lawsuits, tax filings, and other records may still be public or subject to disclosure. A trust also cannot keep an asset out of probate if the asset remains titled solely in the deceased person’s name.
Privacy is one factor to consider, not an automatic reason to create a trust. The appropriate plan depends on asset ownership, family circumstances, incapacity concerns, and administrative goals. An attorney can compare the public probate process with the privacy benefits and ongoing responsibilities of a trust.
Identify Assets That Bypass Probate Through Beneficiary Forms or Joint Ownership
Not every asset passes through a will. Life insurance policies, retirement accounts, payable-on-death bank accounts, and transfer-on-death investment accounts generally pass to the people named on their beneficiary forms. Property held jointly with rights of survivorship may also pass directly to the surviving owner, depending on the title and ownership arrangement.
These transfers may occur even when the will says something different. For example, a former spouse may remain listed as a retirement account beneficiary after divorce, or a newly born child may not appear on an older beneficiary form. Reviewing beneficiary designations is essential whenever someone creates or updates an estate plan.
Joint ownership also requires careful planning. Adding another person to an account or deed may affect control, creditor exposure, taxes, and the eventual distribution of property. It may also create an unintended gift or family conflict. Beneficiary forms and ownership records should be coordinated with the will, trust, and other planning documents instead of being treated as separate paperwork.
Address Intestacy Without a Valid Will
If a person dies without a valid will, Virginia’s intestacy laws determine who receives probate assets. The result may not match the person’s wishes, particularly in blended families, unmarried relationships, or families with children from prior relationships. The law may provide for a spouse, children, parents, or other relatives based on the family structure and applicable statutes.
Dying without a will also means the person did not formally nominate an executor or state a preferred guardian for minor children. The court appoints an administrator to handle the estate, and a separate court process addresses guardianship. A family member may be appointed, but the outcome is not guaranteed to reflect the deceased person’s preference.
A will cannot control assets that pass through beneficiary forms or joint ownership, but it remains important for assets without another transfer method. The Virginia intestacy statutes explain the distribution rules. Families should not assume those rules will produce the desired result, especially when relationships or family finances are complicated.
Meet Virginia’s Small-Estate Requirements
Virginia provides a simplified procedure for certain small estates. Under the current Virginia statute, a small-estate affidavit may be available when the qualifying estate property falls within the statutory limit, which is generally $100,000, and other requirements are met. The affidavit is not automatically available for every estate under that amount.
The person seeking to collect the property may need to wait for the required period, provide specific information, confirm that no personal representative has been appointed, and satisfy other statutory conditions. Real estate, creditor claims, jointly owned property, and assets with beneficiary designations may require separate analysis. The procedure also does not excuse anyone from paying valid debts or distributing property to the correct beneficiaries.
Because the requirements are technical and may change, families should review the current Virginia small-estate statute before relying on an affidavit. If the estate does not qualify, formal probate may still be necessary.
Why Does a Virginia Will Still Matter?
A revocable living trust can be a valuable part of an estate plan, but it does not make a will unnecessary. In Virginia, each document serves a different purpose. A trust generally controls assets transferred into it, while a will controls certain assets that remain in your individual name and provides instructions for administering your probate estate.
A will can also address family concerns that a trust may not cover as directly. It allows you to nominate a guardian for minor children, name the person you want to serve as executor, and leave specific items to family members or other beneficiaries. If you have a trust, a pour-over will can provide an additional layer of protection for assets that were not transferred to the trust during your lifetime.
Your will should work alongside your trust, beneficiary designations, property titles, power of attorney, and medical planning documents. An inconsistency between these documents can create confusion or produce a result you did not intend. A Virginia estate planning attorney can review the full plan and help coordinate it with your family structure, property, and long-term goals.
Name a Preferred Guardian for Minor Children
A will allows you to nominate a preferred guardian for your minor children. You can also name an alternate guardian in case your first choice cannot serve. This gives the court important information about your wishes if you die while your children are still minors.
Your nomination does not automatically appoint the guardian. A Virginia court must still review the circumstances and determine what serves the child’s best interests. Even so, a clear nomination can help the court understand your preferences and may reduce uncertainty among relatives.
Without a will, the court will decide guardianship based on the circumstances and applicable Virginia law. That decision may not match your choice. This Virginia estate planning guidance on naming guardians explains why a trust does not replace this important function of a will.
When choosing a guardian, consider the person’s relationship with your children, age, health, location, parenting approach, and ability to manage daily responsibilities. Discuss your wishes with the person before naming them, and review the nomination after major family changes.
Choose an Executor and State Final Distribution Wishes
Your will names an executor, also called a personal representative, to manage the probate estate. This person may collect assets, pay valid debts and expenses, complete required filings, and distribute property according to your instructions. You can also name a successor executor if your first choice cannot serve.
A will gives you a place to identify who should receive property that passes through probate. You may leave assets to a spouse, children, other relatives, friends, or charitable organizations. Clear instructions can make administration easier and reduce conflict among beneficiaries.
The executor does not control every asset you own. Property held in a trust, jointly owned property, and accounts with beneficiary designations may pass outside the will. Your executor instructions should therefore be coordinated with account ownership and beneficiary forms. This overview of wills and trusts in Virginia explains how each document affects estate administration.
When selecting an executor, consider the person’s reliability, organization, location, and willingness to handle financial and family responsibilities. The best choice is not always the oldest child or closest relative. It may be a trusted family member, friend, or qualified professional.
Create Testamentary Trusts for Young or Vulnerable Beneficiaries
A will can create a testamentary trust, which takes effect after your death. This arrangement may help when a beneficiary is a minor, has difficulty managing money, or needs ongoing support. Instead of giving the beneficiary an entire inheritance immediately, the will can direct a trustee to manage the assets under specific instructions.
For example, the trust might permit payments for education, health care, housing, or other needs. It may also provide for distributions at certain ages or in stages. These terms allow you to provide financial support while delaying outright control until the beneficiary is better prepared to manage the property.
A testamentary trust differs from a living trust because it is created through the will and generally becomes active during estate administration. If a beneficiary receives public benefits, a carefully structured special needs trust may be more appropriate. This Virginia trust planning resource offers additional insight into trust planning for young or vulnerable beneficiaries.
The will should identify the trustee and provide practical instructions for managing the trust. You should also name a successor trustee and explain when the trust should end. An attorney can help tailor those terms to the beneficiary’s needs.
Use a Pour-Over Will for Assets Outside the Trust
If you have a revocable living trust, a pour-over will can direct certain assets left outside the trust into it after your death. The will serves as a safety net for property that was not retitled, newly acquired assets, or accounts that were overlooked during the trust-funding process.
A pour-over provision does not mean the asset automatically avoids probate. Property covered by the provision may still pass through probate before transferring to the trustee. The benefit is that the property can ultimately be managed under the trust’s instructions rather than distributed under Virginia’s intestacy rules.
A pour-over will works best when paired with careful trust funding and regular reviews. Confirm that major accounts, real estate, and other assets are titled correctly, and make sure beneficiary designations support the overall plan. This explanation of how pour-over wills work with trusts provides helpful context.
Keep in mind that a pour-over will is not a substitute for transferring assets to the trust during your lifetime. Proper funding can help the trust achieve its intended purpose, including avoiding probate for eligible assets and allowing a successor trustee to manage them if you become incapacitated.
Address Personal Property and Later-Acquired Assets
Some of the most meaningful possessions are not large financial accounts. Jewelry, family photographs, furniture, artwork, firearms, and heirlooms may carry significant emotional value. A will can identify specific gifts and state who should receive them, helping reduce disagreements among family members.
A will can also address property acquired after the trust was created or assets that were never transferred into the trust. This catchall function helps ensure that property does not fall through the cracks. Specific instructions should remain current, especially if you sell an item, acquire a replacement, or change your mind about a gift.
Consider keeping a separate personal property memorandum if Virginia law and your estate planning documents permit that approach. Your attorney can explain whether the memorandum is legally appropriate and how your will should reference it. This estate planning guidance on wills and personal property explains why these belongings deserve specific attention.
Use clear descriptions when identifying personal property. For example, include identifying details for jewelry, artwork, or collectibles rather than relying only on a general category. Store the list with your estate planning documents and update it when your belongings or wishes change.
Recognize What a Will Cannot Do for Lifetime Incapacity or Privacy
A will generally takes effect at death. It does not manage your property if you become unable to make financial decisions during your lifetime. For that situation, your plan may need a durable financial power of attorney, a revocable trust with successor trustee provisions, or both.
A will also does not provide privacy for assets that pass through probate. Once filed with the appropriate court, it becomes part of the public probate record, along with related filings that may reveal information about the estate and its administration.
A properly funded trust may offer more privacy for assets held in the trust, but it does not replace every supporting document. Beneficiary forms, joint ownership arrangements, powers of attorney, and medical directives still require careful coordination. Reviewing the differences between wills and trusts in Virginia can help clarify which document addresses each part of your plan.
A will also cannot override certain beneficiary designations or ownership rights. For example, an account with a valid beneficiary form may pass according to that form rather than the will. Reviewing all documents together helps ensure your estate plan reflects your current wishes.
How Do a Virginia Living Trust and Will Work Together?
A Virginia living trust and will are not competing documents. They address different parts of an estate plan and should be prepared to work together. A revocable living trust can hold and manage property during your lifetime, provide instructions for distributing that property after death, and name a successor trustee to manage trust assets if you become unable to do so.
A will fills important gaps. It can name your preferred guardian for minor children, appoint an executor, address property that was not transferred to the trust, and create a pour-over plan for assets left outside the trust. Beneficiary designations, property titles, powers of attorney, and health care documents should support the same instructions.
Because each document affects the others, it helps to review the entire plan with a Virginia estate planning attorney. The right approach depends on your family, property, financial accounts, and concerns about incapacity, privacy, and probate.
Coordinate the Trust, Pour-Over Will, and Incapacity Documents
A complete plan may include a revocable living trust, pour-over will, durable financial power of attorney, and advance medical directive. Each document addresses a different need, so creating one does not eliminate the value of the others.
The trust controls property properly transferred to it. The pour-over will addresses assets left outside the trust. A durable financial power of attorney gives an agent authority to handle certain non-trust matters if you cannot manage them yourself. An advance medical directive explains your health care preferences and identifies the person who may make medical decisions for you.
Review these documents as one plan. Names, successor appointments, distribution instructions, and incapacity provisions should not conflict. Outdated or inconsistent documents can create confusion for your family when they need clear guidance.
Use a Pour-Over Will to Catch Unfunded or Overlooked Assets
A pour-over will acts as a backup for property still held in your individual name when you die. It directs that property into your trust, where the trustee can distribute it according to the trust’s instructions. This can help preserve one overall plan for your beneficiaries.
For example, you may transfer your home and investment accounts to a trust, then open a new bank account without updating its ownership. The pour-over will may direct that account to the trust after your death. It can also address personal property or another asset you overlooked.
The will does not fund the trust during your lifetime. You still need to retitle appropriate assets and review beneficiary designations. This Virginia explanation of pour-over wills explains why the document serves as a backup rather than a replacement for trust funding.
Understand Why Pour-Over Assets May Still Go Through Probate
A pour-over will does not transfer property into the trust immediately. Property held in your individual name at death generally must pass through probate before the will can direct it to the trust. The trust may ultimately receive the property, but court administration may come first.
That distinction can affect privacy, timing, and administrative work. Assets already titled in the trust may avoid probate, while overlooked assets covered by the pour-over will may require the personal representative to file the will, notify interested parties, address debts, and complete other required steps.
This is why careful funding matters. A Virginia trust and probate overview explains that a pour-over will can protect against missed assets, but it does not eliminate probate for those assets.
Coordinate Guardianship Nominations With Trust Instructions
If you have minor children, your will can name the person you prefer to serve as guardian if you die or become unable to care for them. A living trust cannot nominate a legal guardian. The court considers your nomination along with the children’s best interests and other relevant circumstances.
Your trust can still provide financial support. It may explain how inherited property should be managed, name a trustee, and set conditions for distributions at different ages. The guardian and trustee may be the same person, but they serve different roles.
A guardian handles daily care and major decisions for the children. A trustee manages trust property. Consider backup choices for both roles and discuss your wishes with the people you name. This Virginia guardianship and trust guidance can help clarify how the documents fit together.
Align the Trust, Will, Beneficiary Forms, and Property Titles
Your estate plan includes more than the documents you sign. Ownership records and beneficiary forms can determine who receives an asset, sometimes taking priority over instructions in your will or trust.
Retirement accounts, life insurance policies, and payable-on-death accounts typically pass to the listed beneficiary. Joint ownership may also affect what happens when an owner dies. If these arrangements conflict with your trust, an asset may not be distributed as you intended.
Review titles and beneficiary forms for your home, bank accounts, investments, insurance policies, retirement plans, and business interests. A Virginia revocable trust planning guide explains why a trust generally applies only to assets transferred to it or properly coordinated with it. Recheck your records after marriage, divorce, adoption, birth, death, or a major change in family circumstances.
Pair the Trust Plan With a Durable Financial Power of Attorney
A successor trustee can manage property held in the trust if you become incapacitated. The trust may not cover every financial matter, however. Assets still held in your individual name and certain personal or legal matters may require a durable financial power of attorney.
This document lets you appoint an agent to handle tasks such as paying bills, managing accounts, signing documents, or dealing with property. The agent’s authority depends on the document’s language and applicable Virginia law, so the power of attorney should fit with your trust and other planning documents.
Your agent and successor trustee can be the same person, but that choice requires care. Both roles carry significant responsibilities. Clear instructions and accessible records may help your family avoid seeking a court-supervised conservatorship. The Virginia State Bar’s estate planning resources offer general information about powers of attorney and related documents.
Add an Advance Medical Directive and Health Care Instructions
A will and trust do not control every medical decision during your lifetime. An advance medical directive can name a health care agent and describe your preferences if you cannot communicate or make decisions. You may also need a HIPAA authorization so your chosen individuals can receive relevant medical information.
Discuss your wishes with your agent and close family members before an emergency occurs. Your instructions may address life-prolonging treatment, pain management, organ donation, or preferred care arrangements. Give a copy to your physician and make sure your agent knows where to find the original.
Virginia planning may involve a health care power of attorney, HIPAA waiver, living will, and declaration of guardian. Reviewing these documents with your financial plan can help identify gaps. This Virginia estate planning overview provides additional information about these health care provisions.
Treat the Pour-Over Will as a Safety Net, Not a Substitute for Funding
A pour-over will is an important backup, but it should not be the primary way your trust receives property. The more assets left outside the trust, the more likely your family may need probate before those assets can be transferred. That can add paperwork, expense, and delay.
After signing the trust, determine whether each asset should be retitled, assigned, or connected through an updated beneficiary designation. Keep a record of completed transfers. Review it when you acquire property, refinance a home, open an account, or change an insurance policy.
Some assets, including certain retirement accounts, may remain outside the trust for tax or administrative reasons. Your attorney can help coordinate their beneficiary designations with the rest of your plan. Treat the pour-over will as a safety net, while viewing trust funding and regular reviews as ongoing parts of your estate plan.
How Can You Choose the Right Virginia Estate Plan?
Choosing between a will, a revocable living trust, or a combination of documents depends on more than the value of your property. Your family structure, real estate holdings, privacy concerns, health, business interests, and plans for future care all play a role. A Virginia estate plan should reflect how you own property and who should manage it if you cannot make decisions for yourself.
For some families, a will may provide clear and practical instructions. Others may benefit from a living trust that keeps certain assets out of probate and provides detailed instructions for management and distribution. Most people also need supporting documents, including a durable financial power of attorney and an advance medical directive.
There is no single estate plan that works for every Virginia resident. The right approach should account for your goals, relationships, assets, and concerns about incapacity. Reviewing those details with a Virginia estate planning attorney can help you choose documents that work together instead of relying on a single form.
Decide When a Will Fits a Straightforward Estate
A will may be a practical choice when your estate is relatively simple, your beneficiaries are clear, and you are comfortable with probate. It may work well if you own limited property, have no real estate in another state, and want adult beneficiaries to receive their inheritances outright.
A will can name an executor, identify beneficiaries, describe your wishes for personal property, and nominate a guardian for minor children. It can also create a testamentary trust for a child or another beneficiary who should not receive an inheritance all at once.
A will does not manage your property during your lifetime or provide instructions for financial decisions if you become incapacitated. Assets passing under the will generally go through probate, and related court filings may be available to the public. Before choosing this approach, review how your assets are titled and whether beneficiary designations already control their distribution.
Consider When a Living Trust May Help With Privacy or Incapacity Planning
A revocable living trust is created during your lifetime, and you generally remain in control of the trust property while you are alive. You can serve as the initial trustee and name a successor trustee to take over if you become unable to manage the trust or after your death.
When assets are properly transferred to the trust, the successor trustee can often manage and distribute those assets without a separate probate process. This may provide greater privacy and more direct administration, although a trust does not eliminate every court proceeding or filing.
A living trust may be useful if you want a plan for possible incapacity, own property in more than one state, or want to distribute assets over time. It also requires careful funding and recordkeeping. A signed trust that never receives ownership of the intended assets may not produce the results you expect. This Virginia comparison of wills and trusts explains several factors to consider.
Plan for Blended Families, Minors, and Vulnerable Beneficiaries
Blended families often need more detailed planning than a simple instruction to divide everything equally. You may want to provide for a current spouse while preserving assets for children from a prior relationship. You may also want beneficiaries to receive property at different times or under different conditions.
A trust can provide income or housing support for one person while preserving the remaining assets for other beneficiaries. It can delay distributions until a child reaches certain ages or completes educational milestones. These instructions can reduce the risk that a young beneficiary receives a large inheritance before they are prepared to manage it.
A trustee can oversee trust property and follow the instructions you set out. Your plan should identify backup trustees and explain what should happen if a beneficiary dies, becomes disabled, or experiences financial problems. Trust instructions should also match your beneficiary forms and property titles. More information about trust planning for blended families may help you identify issues to discuss with counsel.
Address Special-Needs Planning With an Appropriate Trust
If a beneficiary receives needs-based government benefits, an outright inheritance could affect eligibility. Leaving money directly to that person may create problems even when your intention is to provide long-term support.
A special needs trust may allow assets to pay for supplemental expenses without unnecessarily placing the beneficiary’s benefits at risk. Depending on the circumstances, the trust might cover education, transportation, recreation, technology, or personal care while public programs continue to address qualifying basic needs.
The appropriate structure depends on who contributes the assets, the beneficiary’s age, and the benefit programs involved. A first-party trust, third-party supplemental needs trust, or another arrangement may be appropriate in different situations. The document should name a trustee who understands the beneficiary’s needs and can maintain accurate records.
Special-needs planning should be coordinated with the person’s care plan, benefits, and family circumstances. Before naming a beneficiary in a will, trust, retirement account, or insurance policy, review the possible consequences with an attorney. This overview of trusts and government-benefit eligibility offers useful background.
Account for Businesses, Multiple Properties, and Out-of-State Real Estate
A basic will may not provide enough structure when you own a business, several properties, or real estate outside Virginia. Each asset may have separate ownership records, management concerns, transfer requirements, and liability considerations.
A trust may provide centralized instructions for property management and allow a successor trustee to step in if you cannot manage the assets. It may also reduce the need for a separate probate proceeding in another state when out-of-state real estate is properly transferred to the trust. The result depends on correct titling and the laws of the state where the property is located.
Business owners should review operating agreements, shareholder agreements, buy-sell provisions, and succession plans. Transferring a business interest to a trust may require consent or specific documentation. Real estate should be reviewed parcel by parcel, including mortgages, insurance, ownership records, and transfer restrictions.
Because these decisions can affect both your estate and your family’s financial security, coordinate the trust with your other legal documents. This Virginia trust planning resource discusses situations in which a trust may be useful for complex assets.
Weigh Cost, Control, Privacy, Timing, and Family Protection
A living trust usually requires more work at the beginning than a basic will. You may need to retitle bank accounts, transfer real estate, update business records, and maintain a current list of trust property. These steps create additional responsibility, but they may provide meaningful benefits.
Consider whether avoiding probate for properly funded trust assets matters to your family. You may also value private administration, quicker access to assets, or a clear plan for someone to manage property if you become incapacitated. A trust can provide ongoing instructions for a minor or vulnerable beneficiary instead of requiring an outright distribution.
A will may be easier to maintain when your estate and family circumstances are uncomplicated. It may also be a good fit if you are comfortable with probate and do not need continuing trust management.
The right choice involves tradeoffs, not just document prices. Compare the likely costs, level of control, privacy, administration time, and protection available for your beneficiaries. A revocable living trust overview can help you prepare questions for an estate planning consultation.
Look Beyond Estate Size When Considering a Trust
The value of your estate is one factor, but it should not decide the issue by itself. A person with a modest estate may still benefit from a trust if they own a second home, have a child with special needs, or want to protect an inheritance from poor financial decisions.
Family complexity may matter more than net worth. A trust can help coordinate support for a surviving spouse, children from different relationships, stepchildren, or beneficiaries who need assistance managing money. It can also provide a structure for property that must be held and managed over time.
Some planning resources identify assets exceeding $200,000 as one reason to consider a trust, but that figure is not a universal rule. The type of assets, how they are titled, and your family’s needs may matter more than the total amount.
Ask what could make administration difficult for your family, not just how much property you own. A review of ownership records and beneficiary designations can show whether a trust would add practical value. This discussion of when a Virginia revocable trust may help covers several factors beyond estate size.
Coordinate Estate Planning With Divorce, Adoption, Custody, or Guardianship Changes
Major family changes should prompt an estate plan review. Divorce, separation, remarriage, adoption, the birth of a child, or the death of a beneficiary can affect your choices for property distribution and decision-making authority.
A divorce may require updates to your will, trust, beneficiary designations, financial power of attorney, and advance medical directive. Virginia law may affect some provisions after a divorce, but relying on automatic changes can leave gaps or produce results that do not match your current wishes. Review every document rather than assuming one update will address the entire plan.
Adoption and custody changes may affect guardianship nominations and inheritance instructions. If you have minor children, remember that a will can nominate a preferred guardian, while a living trust cannot appoint a legal guardian by itself. The court considers the child’s best interests when deciding guardianship.
Military service, relocation, and changes in a child’s care needs also deserve attention. Keep your estate plan consistent with custody orders, separation agreements, and current family relationships. The Virginia law addressing guardian nominations in wills is one important part of that review.
How Can You Create, Fund, and Update a Virginia Estate Plan?
Creating an estate plan involves more than signing a will or placing documents in a folder. A well-prepared plan connects your assets, account instructions, family circumstances, and incapacity documents so they work together. Start by gathering information about what you own, how each asset is titled, and who would receive it. Then decide who should manage your property and make important decisions if you become unable to make them yourself.
Your plan may include a will, revocable living trust, durable financial power of attorney, and advance medical directive. It may also involve beneficiary forms, joint ownership arrangements, and instructions for digital accounts. Each document serves a different purpose, so an inconsistency in one part of the plan can affect the rest. Virginia has specific requirements for executing estate planning documents, making it helpful to review the completed plan with a Virginia estate planning attorney.
As you create or update your plan, keep copies of important records and note when each document, account designation, or property transfer was last reviewed. This information can make administration easier for your family and help your attorney identify gaps before they create problems.
Inventory Assets, Ownership, Beneficiary Designations, and Digital Accounts
Start with a complete list of what you own and how each item is titled. Include your home and other real estate, vehicles, bank accounts, investments, retirement accounts, life insurance, business interests, valuable personal property, and debts. An estate is not limited to significant wealth. It may also include furniture, pension benefits, Social Security benefits, and other property, as explained in this overview of Virginia estate planning.
For each asset, record the institution, account number, approximate value, owner, and current beneficiary. Also identify digital assets, including online financial accounts, photographs, cryptocurrency, domain names, and subscriptions. Store access instructions securely rather than placing passwords directly in a will, which could become part of a public court file. Review the inventory when you buy, sell, inherit, or transfer property.
Identify Beneficiaries, Trustees, Executors, Guardians, and Backup Agents
Name the people or organizations you want to receive your property, then choose the individuals who will carry out your instructions. An executor administers an estate under a will, while a trustee manages property held in a trust. Choose people who are organized, dependable, and willing to take on these responsibilities. Naming backup fiduciaries can help if your first choice cannot or does not want to serve.
Parents should also nominate a preferred guardian for minor children. A trust can manage money for a child, but it does not replace a will for naming a guardian in Virginia. This explanation of wills and trusts for Virginia families notes that a court still evaluates guardianship based on the child’s best interests. Speak with the people you nominate so they understand your wishes before an emergency occurs.
Sign, Witness, Notarize, and Store Documents Correctly
Estate planning documents must be executed in the correct form. Virginia wills, trusts, powers of attorney, and medical directives can have different signing and witnessing requirements. A will may also include a self-proving affidavit, which can simplify the process of proving its validity after death. Notarization does not replace required witnesses, and the formalities depend on the document.
Use an estate planning attorney or another qualified professional to confirm that each document was signed properly. Virginia has specific requirements for signing, witnessing, and notarization. Keep the originals in a secure but accessible location, and tell your executor or trusted family member where to find them. If no one can locate the documents, even a carefully prepared plan may be difficult to use when it is needed.
Retitle Bank Accounts, Investments, and Real Estate When Appropriate
A revocable living trust generally manages property transferred to it or otherwise directed to it through appropriate documents. After signing the trust, review each asset with your attorney and financial institutions to determine whether ownership should change. This process may involve retitling a bank or investment account, preparing and recording a deed, or assigning certain property to the trust.
Funding decisions require care because not every asset should be handled in the same way. Some property may remain in your individual name, pass through a beneficiary designation, or require another planning method. This explanation of revocable trust ownership requirements illustrates why signing a trust alone may not be enough. Keep copies of transfer documents and confirmation letters so your successor trustee can identify the trust’s assets.
Coordinate Retirement Accounts, Insurance, Joint Ownership, and Payable-on-Death Forms
Beneficiary designations can control who receives retirement accounts, life insurance proceeds, and accounts with payable-on-death or transfer-on-death instructions. These assets may pass outside probate, but their instructions must match the broader estate plan. A will generally cannot change a beneficiary form that names someone else.
Review primary and contingent beneficiaries after creating or updating your estate plan. Consider how each designation interacts with a trust, spouse, minor children, or a beneficiary who receives public benefits. Retirement accounts also involve federal tax rules, so do not name a trust without understanding the possible consequences. Trusts may form part of a retirement plan, but beneficiary choices require careful coordination with federal tax rules.
Keep Trust Records Current and Confirm Successor Trustee Access
A trust works best when its records are organized and easy to understand. Keep a current list of trust-owned assets, account statements, deeds, insurance information, tax records, and important contact details. Update the list when you open an account, sell property, refinance a home, or move an asset into or out of the trust.
Your successor trustee should know how to locate the trust and access essential information without receiving unnecessary private details during your lifetime. Ask your attorney whether the successor trustee may need a certification of trust or another document. Coordinate the trust with a durable financial power of attorney and advance medical directive, since these documents address decision-making during incapacity. This Virginia revocable trust guidance explains why these documents should be considered together.
Review the Plan After Marriage, Divorce, Separation, Adoption, Birth, or Death
Family changes can make an estate plan inaccurate quickly. Review your documents after marriage, divorce, legal separation, adoption, the birth of a child, or the death of a beneficiary, executor, trustee, guardian, or agent. You may need to change distribution instructions, update fiduciary appointments, or revise beneficiary forms.
Do not assume that a divorce automatically updates every document or account. Retirement plans, insurance policies, and jointly owned property may follow separate rules. Revisit the plan after a change in parental rights or guardianship, too. A regular review helps keep your will, trust, account designations, and incapacity documents consistent. This estate planning review guidance explains why changes in laws, assets, tax rules, and family circumstances can justify an update.
Reassess the Plan After Relocation, Military Moves, Property Changes, or Business Changes
Moving can affect your estate plan, particularly if you relocate to another state, buy property elsewhere, or maintain homes in multiple jurisdictions. Military families may also experience frequent moves, changes in duty station, and updates to powers of attorney. Ask an attorney to review the plan after relocating instead of assuming every document will operate the same way in a new state.
Schedule another review after buying or selling real estate, starting or closing a business, receiving an inheritance, or experiencing a significant change in debt or assets. Business ownership may require succession documents and a review of operating agreements. Even if your family has not changed, your property may have. Regularly update an estate plan as circumstances change so new assets do not fall outside your intended plan.
Ask a Virginia Beach Estate Planning Attorney to Coordinate the Full Plan
An estate planning attorney can review the entire structure instead of focusing on one document in isolation. That review may include your will, trust, powers of attorney, advance medical directive, property titles, beneficiary designations, and guardianship nominations. The goal is to identify conflicts, missing transfers, outdated instructions, and practical problems your family may face later.
Choose counsel familiar with Virginia law and the needs of families in Virginia Beach and Hampton Roads. Bring your asset inventory, existing documents, account statements, deeds, and questions to the meeting. A Virginia attorney can help confirm that your documents meet state requirements and reflect your goals. Professional Virginia estate planning advice can be especially valuable when you are creating a trust, coordinating several types of assets, or revising a plan after a major family change.
Related Articles
- Do You Need a Will If You Have a Trust in Virginia?
- Will vs. Trust: Which Is Right for You in Virginia?
- Who Should Have a Revocable Trust in Virginia?
- Substantive Legal Questions: Revocable Living Trusts
- Virginia Estate Planning 101
Frequently Asked Questions
Is a living trust better than a will in Virginia?\ Neither document is automatically better. A will may suit a straightforward estate, while a revocable living trust may be useful for incapacity planning, privacy, multiple properties, or beneficiaries who need ongoing support. Many Virginia families use both documents as part of one coordinated estate plan.
Does a living trust avoid probate in Virginia?\ A properly funded trust can generally keep trust-owned assets out of probate. Signing the trust alone is not enough. Eligible bank accounts, investments, real estate, and other property must be transferred to the trust or coordinated with it. Assets left outside the trust may still require probate under a pour-over will.
Do I still need a will if I have a living trust?\ Yes, in most cases. A will can nominate a guardian for minor children, name an executor, address property outside the trust, and direct overlooked assets into the trust. A living trust cannot appoint a legal guardian by itself, although it can provide financial instructions for a child’s inheritance.
Does a revocable living trust protect assets from creditors or reduce taxes?\ Usually not. Because you generally retain control over a revocable trust, its assets may remain available to your creditors and part of your taxable estate. Asset protection and tax planning may require different structures, which should be reviewed with a Virginia estate planning attorney.
When should I update my Virginia estate plan?\ Review your plan after marriage, divorce, separation, adoption, the birth or death of a family member, relocation, military moves, major property changes, or business changes. Also confirm that trust ownership records, beneficiary designations, fiduciary appointments, and incapacity documents still match your wishes.